定義
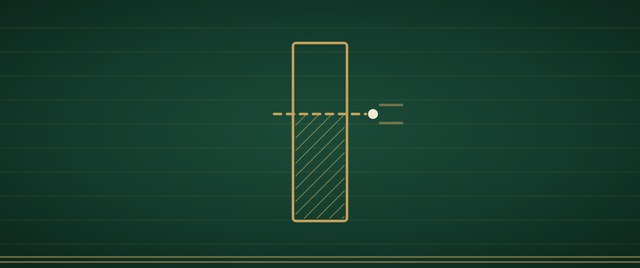
An advance rate is the percentage of a collateral asset's market value that a lender is willing to extend as a loan, effectively setting the maximum borrowing capacity against that asset.
Advance rates vary by asset type because lenders price the risk that collateral could lose value rapidly or become difficult to sell. A diversified portfolio of large-company stocks might carry a higher advance rate than a concentrated single-stock position or an illiquid private fund interest, simply because the lender can sell the former quickly if the borrower defaults. Understanding the advance rate on each type of collateral is essential when families evaluate borrowing strategies through structures like a securities-based line of credit or a margin loan.
As an illustrative example, a lender might extend a hypothetical advance rate of seventy percent against a broad equity portfolio, meaning a family with an illustrative portfolio value of one million dollars could borrow up to seven hundred thousand dollars against it. Against a concentrated position in a single employer's stock, that same lender might offer an advance rate of thirty percent or less, or decline entirely, because a sharp decline in one company's price could destroy collateral value faster than the lender can act.
Advance rates are not static. Lenders can and do reduce them during periods of market stress, precisely when borrowers are most vulnerable. A family that calibrated its borrowing to a seventy-percent advance rate may find that rate cut to fifty percent mid-crisis, triggering an unexpected collateral shortfall. This dynamic, sometimes called a procyclical squeeze, is one of the most underappreciated risks in portfolio-secured lending.
A licensed financial professional and attorney should evaluate any specific lending arrangement, as advance rates, terms, and collateral eligibility differ significantly across lenders and structures.
最終レビュー日 August 25, 2026 · 編集方針